
Top Layer 1 blockchains in 2026: ten networks compared
What each network is actually good for, and the trade-off that comes with it.
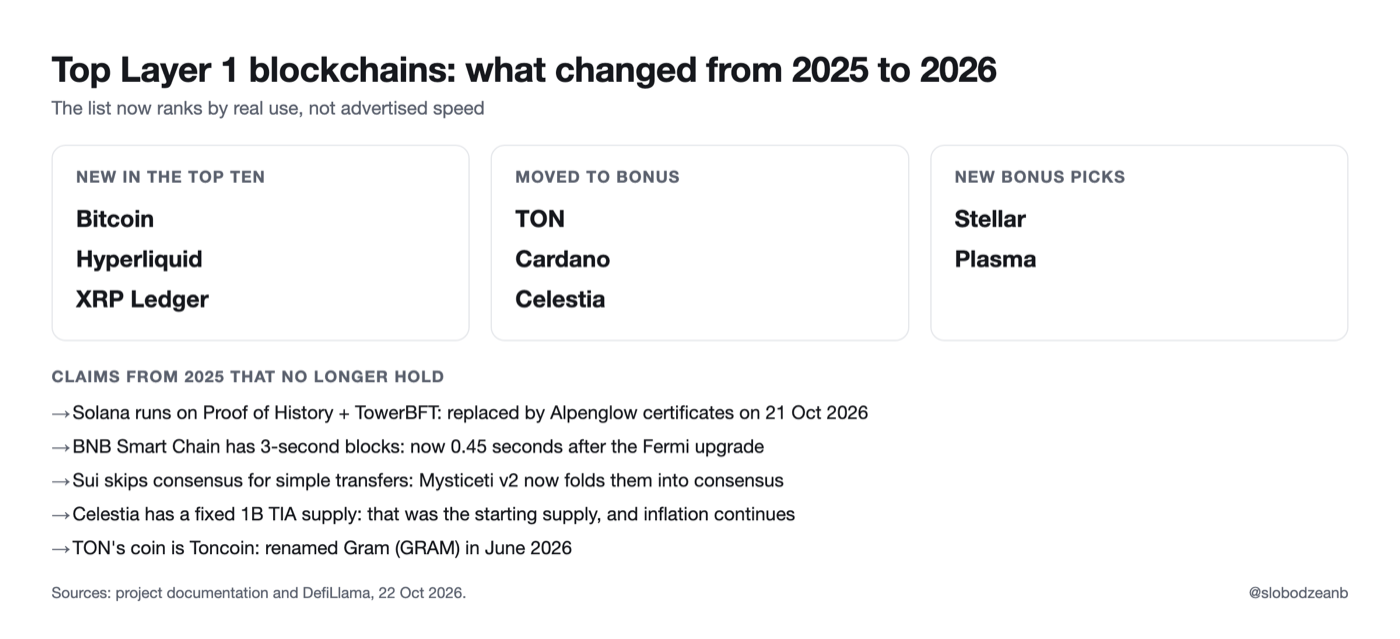
What changed since the 2025 list: Bitcoin, Hyperliquid and the XRP Ledger joined. TON, Cardano and Celestia moved to the bonus picks, alongside Stellar and Plasma.
In this guide
The short version
- Holding crypto with no issuer behind it: Bitcoin
- The widest choice of apps and dollar stablecoins: Ethereum
- Cheap, fast trading and payments: Solana
- Moving USDT, especially between exchanges: TRON
- Familiar Ethereum-style apps at low cost: BNB Smart Chain
- Onchain perpetual futures trading: Hyperliquid
- Narrower strengths: Avalanche (custom chains), XRP Ledger (payments), Aptos and Sui (apps built in the Move language)
I published the first version of this list in April 2025. Eighteen months later, almost every technical line in it needed rewriting. Solana switched to a new consensus system the day before I finished this update. BNB Smart Chain blocks now arrive in under half a second. TON’s native coin has a new name. And several networks once described as never going down have gone down.
So this isn’t a light refresh. It’s a new list built around a better question: not “which chain is fastest?” but what is each network used for, and what do you give up by using it?
Nothing here is investment advice. It’s a map of what each network does well and where it falls short.
What is a Layer 1 blockchain?
A Layer 1 (L1) is a base blockchain with its own consensus (the rules for agreeing on what happened) and its own ledger. Bitcoin, Ethereum and Solana are all Layer 1s.
A Layer 2 (L2), such as Base, Arbitrum or Optimism, processes transactions somewhere else and posts proof or data back to a Layer 1, usually Ethereum. L2s are cheaper to use, but they add their own operators, bridges and withdrawal rules. They’re not on this list.
One change from last year: an L1 doesn’t need to run general-purpose smart contracts to count. That’s why Bitcoin and the XRP Ledger are now on the list.
How I picked the ten
I didn’t rank by token price or advertised speed. I looked at:
- Real economic use: stablecoin balances, trading activity and live applications
- Operating history: outages, exploits and how they were handled
- Access: wallet support, and whether exchanges document deposits and withdrawals on that network
- A distinct purpose: what this network does that the others don’t
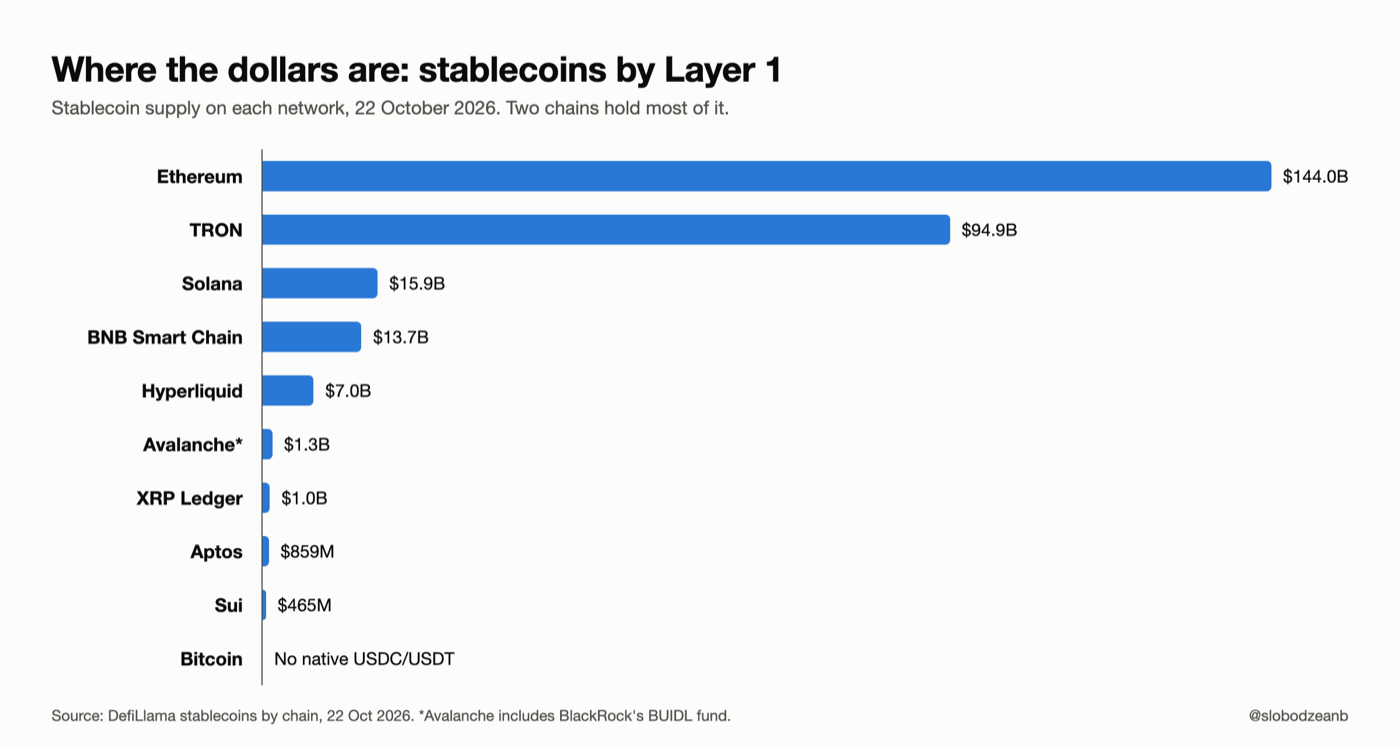
There’s no points score. The data isn’t comparable enough: weighing derivatives trading against remittances would produce a precise-looking number that means nothing. The numbers below are a snapshot from DefiLlama taken on 22 October 2026, plus protocol documentation and incident reports linked in each section.
The ten, side by side
| Network | Best for | Stablecoins | DeFi locked | Speed and fees | Main trade-off |
|---|---|---|---|---|---|
| Bitcoin (BTC) | Holding and sending BTC | None native | $4.4B* | About 10-minute blocks; fee per byte | Slow and costly for small payments |
| Ethereum (ETH) | DeFi and stablecoins | $144.0B | $49.7B | 12-second slots; finality in about 13 minutes | L1 fees add up on small transactions |
| Solana (SOL) | Trading and payments | $15.9B | $5.9B | About 150 ms finality (new; developer figure) | Consensus is one day old; past outages |
| TRON (TRX) | Moving USDT | $94.9B | $5.5B | Paid in “energy” and “bandwidth” | 27 block producers; about 98% of dollars are USDT |
| BNB Smart Chain (BNB) | Low-cost EVM apps | $13.7B | $5.7B | 0.45-second blocks | 21 producers per epoch; mostly bridged dollars |
| Hyperliquid (HYPE) | Perpetuals trading | $7.0B | $2.4B | Trading fees separate from gas | Specialist chain; API outage, market interventions |
| Avalanche (AVAX) | EVM apps and custom chains | $1.3B* | $572M | EVM gas paid in AVAX | Smaller liquidity; the C-Chain isn’t every Avalanche L1 |
| XRP Ledger (XRP) | Payments and issued dollars | $1.0B | $40M | 0.00001 XRP base fee; 1 XRP account reserve | Trusted validator lists; thin DeFi |
| Aptos (APT) | Move apps, native USDC and USDT | $859M | $43M | Gas in APT, can be sponsored | Dollars far exceed DeFi depth |
| Sui (SUI) | Move DeFi and consumer apps | $465M | $497M | Gas plus storage fee, partly rebated | Two chain halts; validators froze stolen funds |
Source: DefiLlama, 22 October 2026. The numbers move daily. Bitcoin’s figure (*) mostly reflects wrapped BTC and other layers, not native Bitcoin DeFi. Avalanche’s stablecoin figure (*) includes BlackRock’s BUIDL fund, which isn’t retail cash.
The ten networks
1Bitcoin BTC
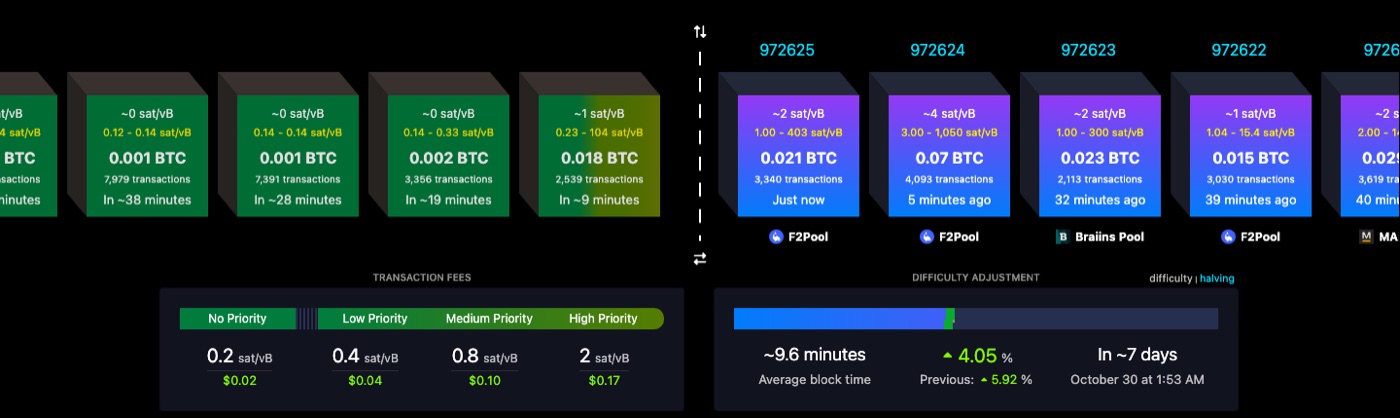
Bitcoin has run since January 2009 with no token sale, no foundation allocation and no company that can freeze coins. New BTC enters circulation through mining, the subsidy is 3.125 BTC per block after the 2024 halving, and supply is capped at roughly 21 million. Blocks arrive about every ten minutes on average, and each extra confirmation makes a payment harder to reverse.
Why it’s here
I left Bitcoin out in 2025 because it doesn’t run general-purpose smart contracts. That was the wrong test. For self-custody and final settlement, Bitcoin is the reference point the other nine get measured against.
The catch
It’s a poor home for dollars. Circle doesn’t issue USDC on Bitcoin, and Tether ended support for its old Omni-based USDT. Fees are bid per byte, so a small payment can cost a lot when blocks are full. Most “Bitcoin DeFi” runs on other layers or wrapped BTC, which add custody and bridge risk.
2Ethereum ETH
Ethereum launched in July 2015 and introduced the smart-contract platform most of crypto still builds on: the Ethereum Virtual Machine (EVM). It runs on proof of stake, with 12-second slots and final settlement about two epochs (around 13 minutes) later.
Why it’s here
It holds the most dollars by a wide margin: $144 billion in stablecoins and $49.7 billion in DeFi in the snapshot. Circle and Tether both issue natively on Ethereum, and apps like Aave, Uniswap, Sky and Lido run here. Much of the cheap, everyday activity has moved to Layer 2 rollups that settle back to Ethereum.
The catch
Fees on the main chain make small transactions inefficient. ETH supply isn’t fixed: staking creates new ETH and fees burn some, so “ETH is always deflationary” is false. In May 2023, the chain briefly stopped finalizing twice while blocks kept coming. The next major upgrade, Glamsterdam, is still in development.
3Solana SOL
Solana launched its mainnet beta in March 2020. It runs programs in parallel when they don’t touch the same accounts, which keeps fees low: the base fee is 5,000 lamports (0.000005 SOL) per signature, before priority fees.
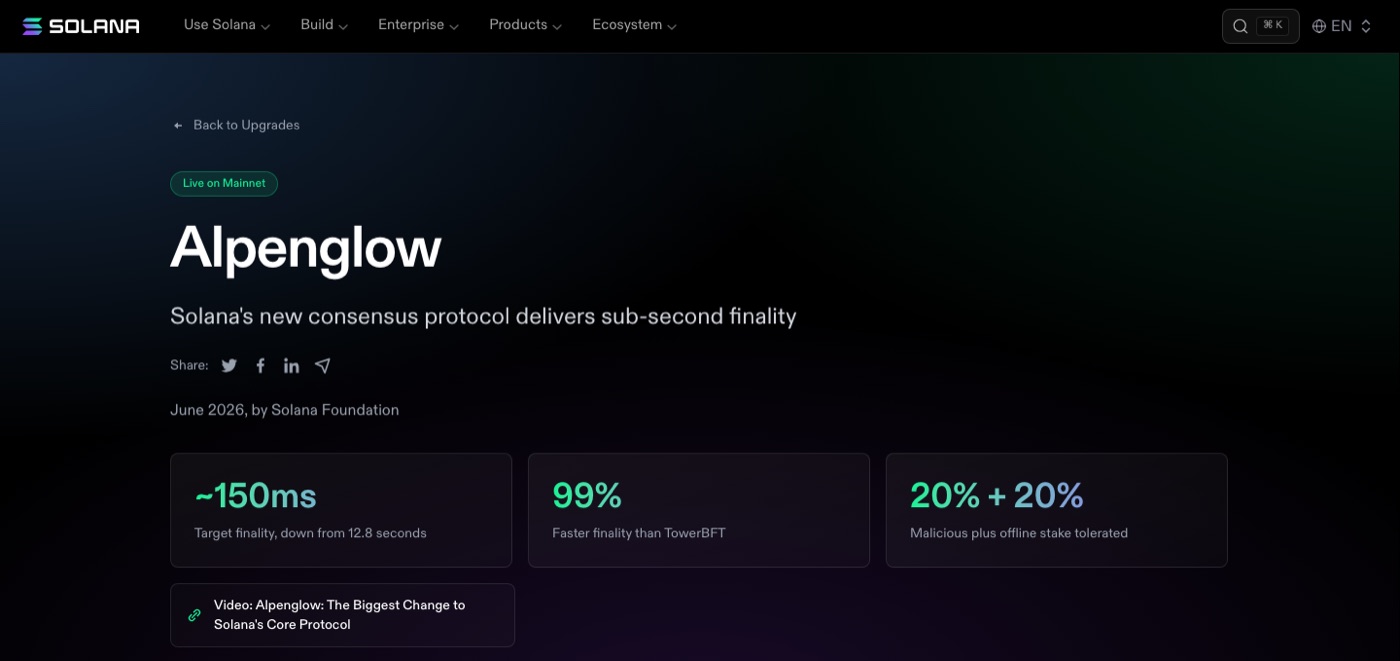
The big change: on 21 October 2026, the first phase of Solana’s Alpenglow upgrade went live. It replaced the old voting system with signed certificates, and the developer team Anza reports about 150 milliseconds to finality. Proof of History, the clock most Solana explainers still describe, no longer paces block production.
Why it’s here
In the 24 hours I captured, Solana’s DEX volume ($2.28 billion) was higher than Ethereum’s main chain. It holds $15.9 billion in stablecoins, with native USDC and USDT. Jupiter, Raydium, Kamino and Jito anchor the ecosystem.
The catch
The new consensus has no track record yet. Solana halted for about five hours in February 2024 after a software bug. And forget the old “65,000 TPS” line: the new system no longer counts votes as transactions, so old and new throughput figures can’t be compared.
4TRON TRX
TRON was founded by Justin Sun in 2017 and moved to its own mainnet in 2018. It runs Solidity-compatible smart contracts and is secured by 27 “Super Representatives” elected by token-holder votes every six hours. Instead of paying gas, users spend “bandwidth” and “energy”, which they can get by staking TRX, renting it or burning TRX.
Why it’s here
TRON holds $94.9 billion in stablecoins, second only to Ethereum, and about 98% of that is USDT. For a lot of people, TRON is how USDT moves between exchanges.
The catch
27 producers is a small group, and large voting blocs concentrate influence. It’s a one-stablecoin network: Circle stopped minting USDC on TRON in February 2024. “Sending USDT costs a cent” isn’t reliable either, because energy pricing changes. Exchange fees can matter more: Kraken charges 1 USDT to withdraw on TRON, with a 6 USDT minimum. DeFi activity is thin compared with the dollar balance.
5BNB Smart Chain BNB
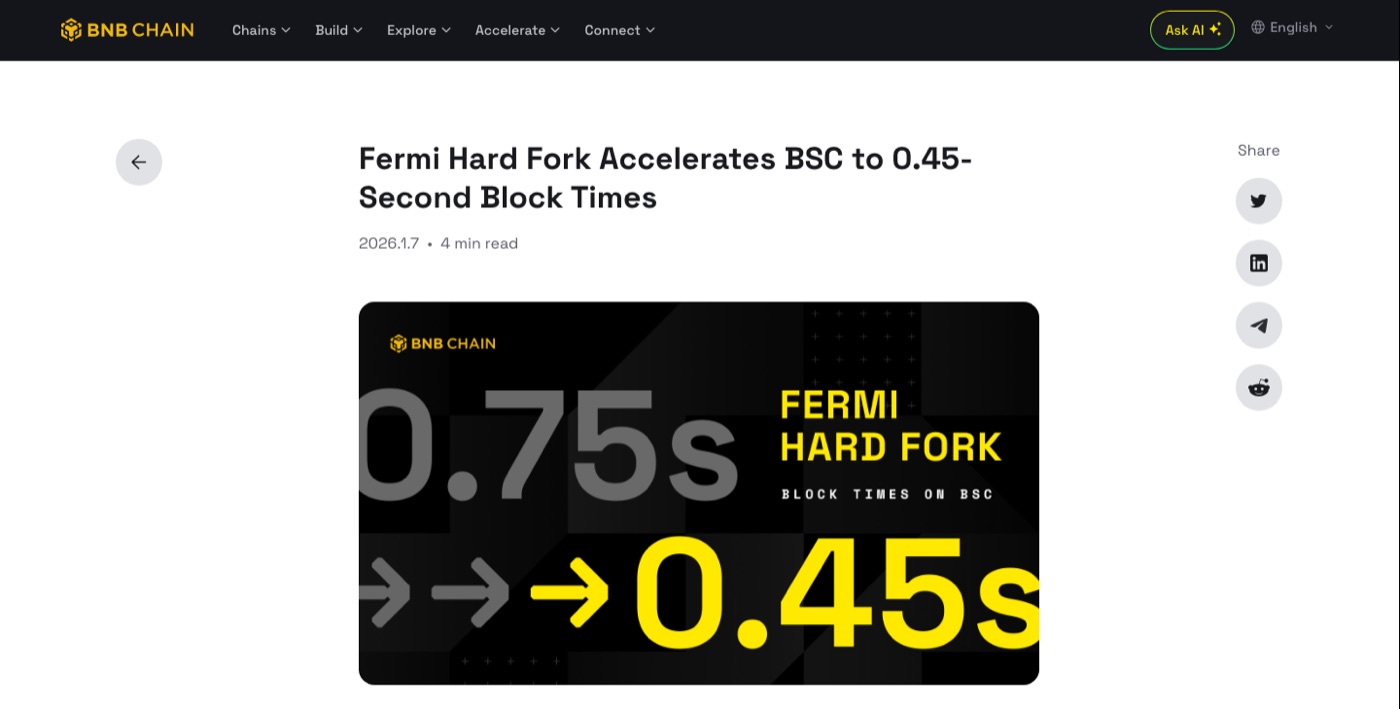
BNB Smart Chain (BSC) launched in September 2020 as an EVM-compatible chain backed by Binance. The Fermi upgrade in January 2026 cut block times to 0.45 seconds; the three-second figure in older articles, including mine, is obsolete. There are 45 elected validators, and 21 of them produce blocks in each epoch.
Why it’s here
Familiar Ethereum tooling at low cost, plus Binance’s distribution. BSC holds $13.7 billion in stablecoins and $5.7 billion in DeFi, led by PancakeSwap and Venus.
The catch
Validation is concentrated, and that has consequences. In October 2022, an attacker exploited the Token Hub bridge and created 2 million BNB (about $586 million at the time). Validators paused the whole chain to contain it. That helped, but it also proved a small group can stop everyone’s transactions. Most dollars on BSC are Binance-pegged versions of USDC and USDT, not tokens issued by Circle or Tether.
6Hyperliquid HYPE
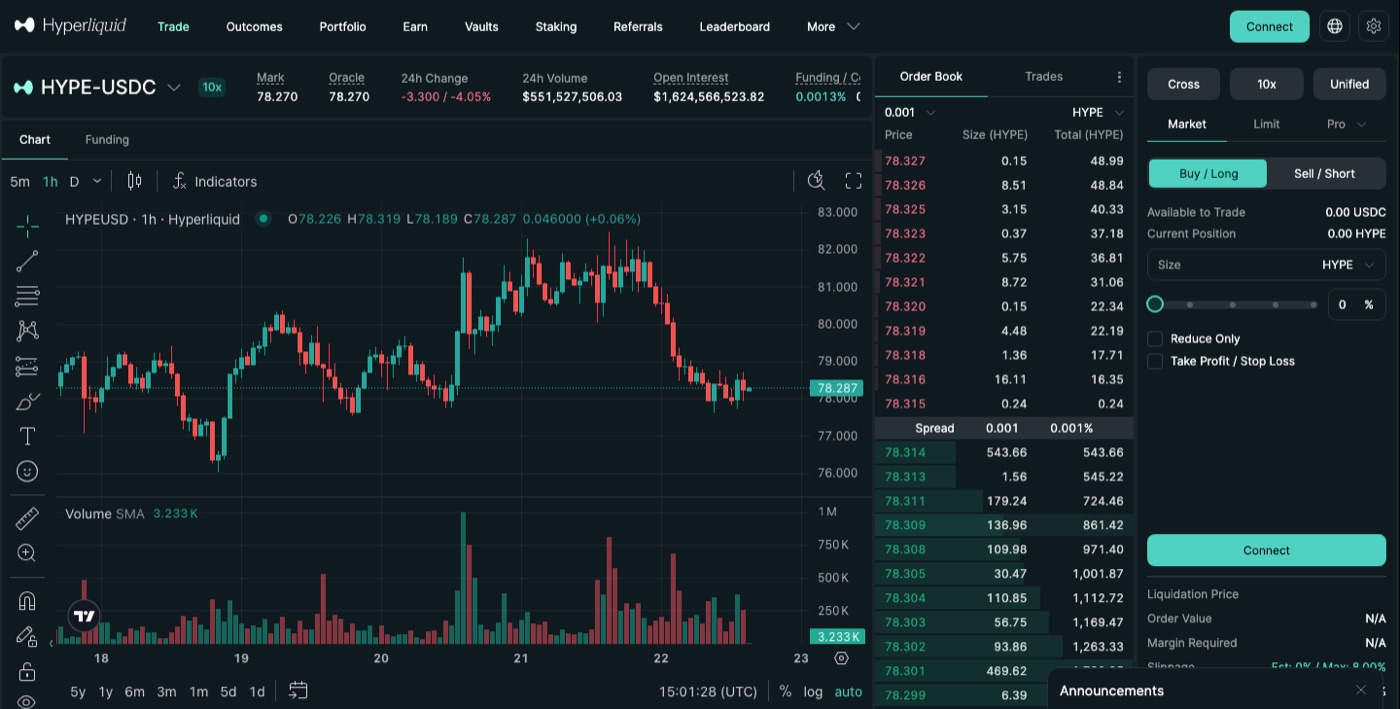
Hyperliquid is a Layer 1 built for trading. One consensus system, HyperBFT, runs two parts: HyperCore (onchain order books for perpetual futures and spot) and HyperEVM (general smart contracts). The team is self-funded, and the HYPE token launched in November 2024.
Why it’s here
It’s one of the few chains where onchain trading is the main business, not a side effect. Hyperliquid held $7 billion in stablecoins (mostly trading collateral) and $2.4 billion in DeFi in the snapshot. Circle now issues native USDC on HyperEVM, so “all Hyperliquid USDC is bridged from Arbitrum” is out of date.
The catch
On 29 July 2025, the main API went down for about 37 minutes. The chain kept producing blocks, but traders couldn’t manage their positions; refunds followed. In March 2025, validators delisted and settled the JELLY market, which shows they can step in. Running a validator requires a 10,000 HYPE self-bond.
7Avalanche AVAX
Avalanche launched in September 2020. Its Primary Network has three chains: the C-Chain runs EVM smart contracts, the P-Chain handles validators and staking, and the X-Chain handles creating and exchanging assets. Teams can also launch independent “Avalanche L1s” (formerly subnets) with their own validators and rules.
Why it’s here
It’s an established EVM ecosystem with native USDC and USDT on the C-Chain, plus apps like Aave, BENQI, LFJ and GMX. It’s also a common home for institutional tokenization experiments.
The catch
It’s much smaller than the top five: $572 million in DeFi. The $1.3 billion stablecoin figure includes BlackRock’s BUIDL fund, which retail users can’t spend. The C-Chain stopped finalizing blocks for about five hours in February 2024. And independent Avalanche L1s don’t share the C-Chain’s security just because they use Avalanche software.
8XRP Ledger XRP
The XRP Ledger launched in June 2012 with payments, issued assets, an order book and an automated market maker built into the protocol. There’s no mining or staking: validators agree using lists of trusted validators. All 100 billion XRP were created at launch, and fees are destroyed.
Why it’s here
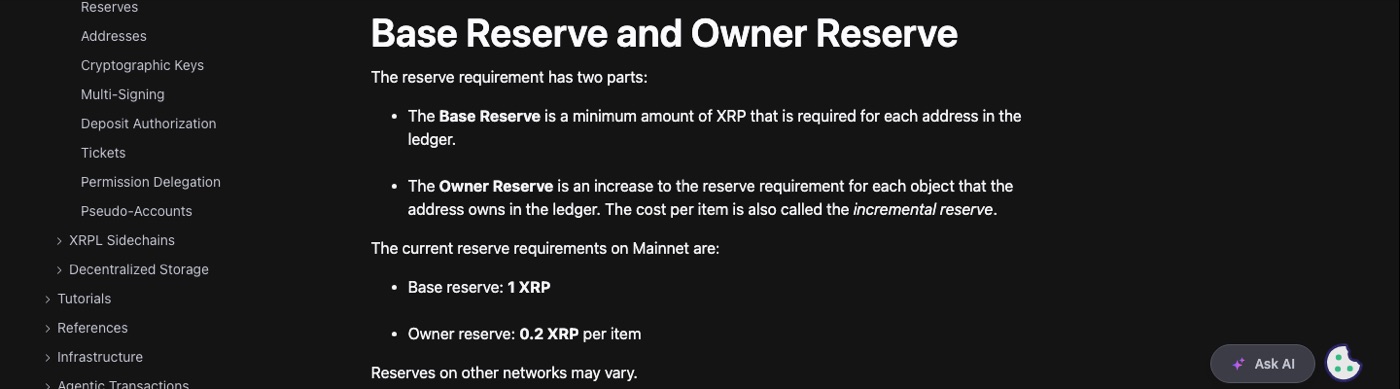
It’s built for payments. The base fee is 0.00001 XRP, and the account reserve dropped to 1 XRP in December 2024 (older guides still say 10 or 20). It now has issuer-native dollars too: Circle’s USDC and Ripple’s RLUSD, with about $1 billion in stablecoins, mostly RLUSD.
The catch
Security depends on validators’ trusted lists overlapping enough. The ledger halted for about 10 minutes in November 2024 and about 64 minutes in February 2025. DeFi is thin ($40 million). At exchanges, a missing destination tag can strand a deposit, and an XRP deposit route doesn’t mean the exchange accepts RLUSD or USDC on the ledger.
9Aptos APT
Aptos was founded by former Meta engineers who worked on the Diem project and launched in October 2022. It uses the Move language and Block-STM, which runs transactions in parallel and re-checks the ones that conflict.
Why it’s here
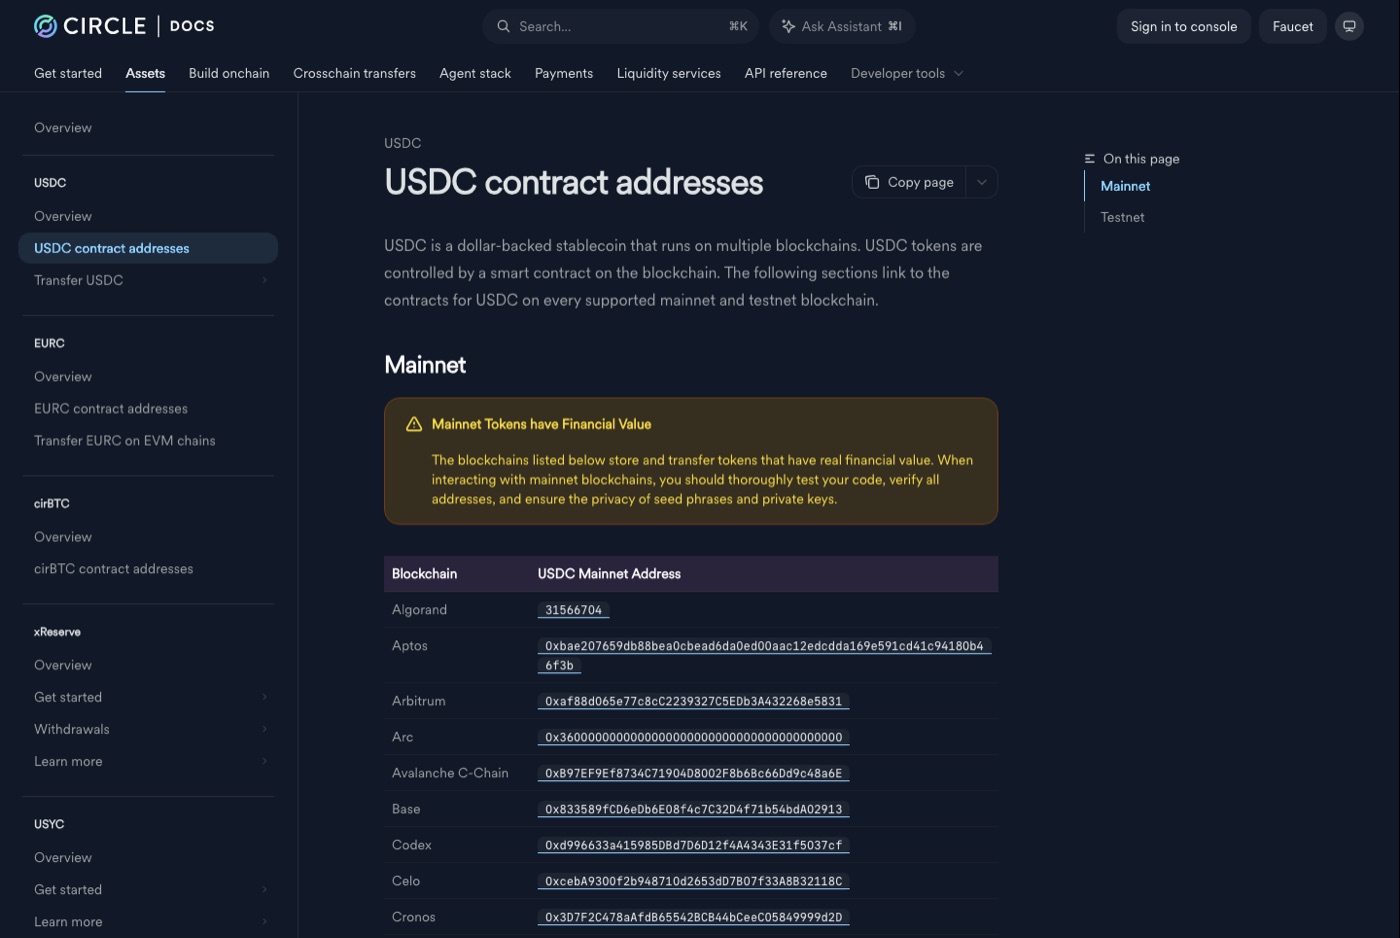
Both Circle and Tether issue natively on Aptos, and it holds $859 million in stablecoins. It’s a real alternative for dollar transfers outside the EVM world.
The catch
Activity looks bigger than the economy behind it. Aptos has $859 million in stablecoins but only $43 million in DeFi, so moving large amounts can be harder than the headline suggests. The official dashboard and DefiLlama report different daily transaction counts (9.5 million and 14.1 million), so treat either with care. Monthly APT emissions are far larger than the amount burned, so the token isn’t deflationary. On 22 October, OKX listed Aptos USDT withdrawals as under maintenance, while deposits and USDC worked normally.
10Sui SUI
Sui was built by Mysten Labs, another ex-Meta team, and launched in May 2023. It treats every asset as an “object”, which lets unrelated transactions run in parallel. Its current consensus, Mysticeti v2, folds transaction checks into consensus; the old “simple transfers skip consensus” explanation is out of date.
Why it’s here
Sui has $497 million in DeFi, more than Aptos, the XRP Ledger or Cardano. Suilend, NAVI, Cetus, DeepBook and Bluefin cover lending and trading, and Circle issues USDC natively.
The catch
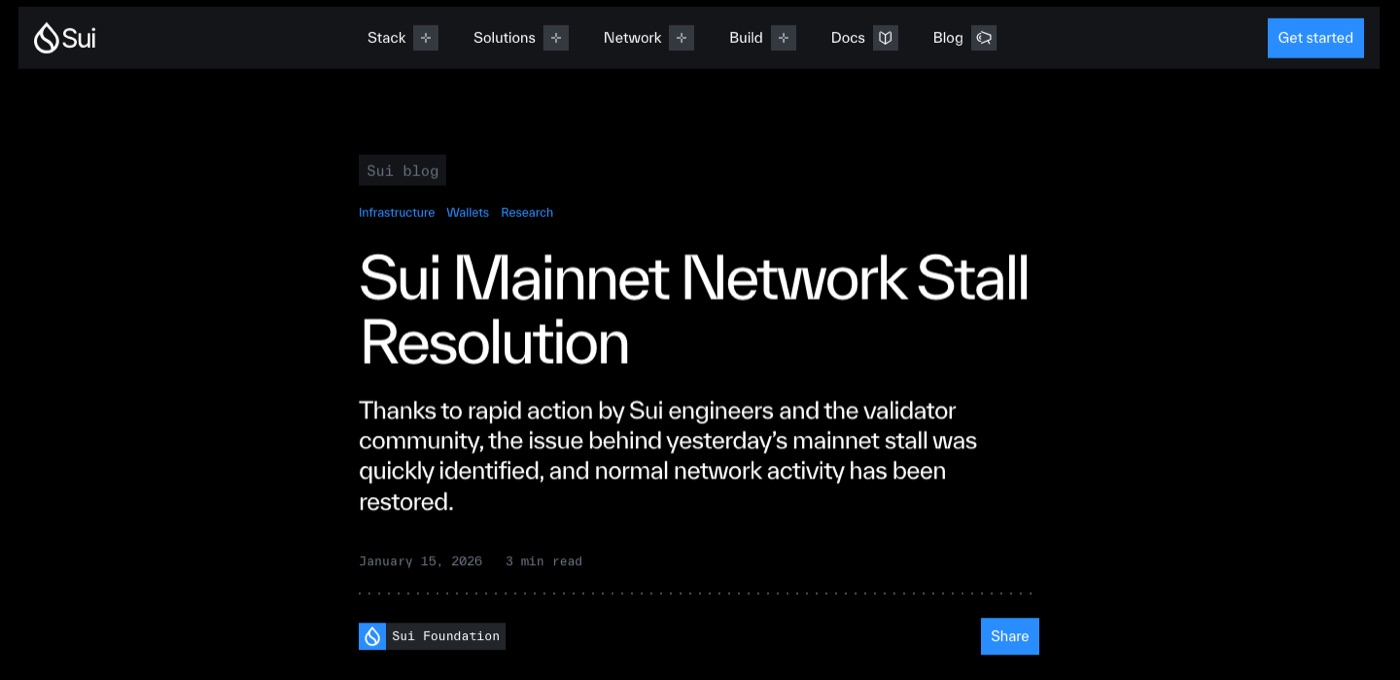
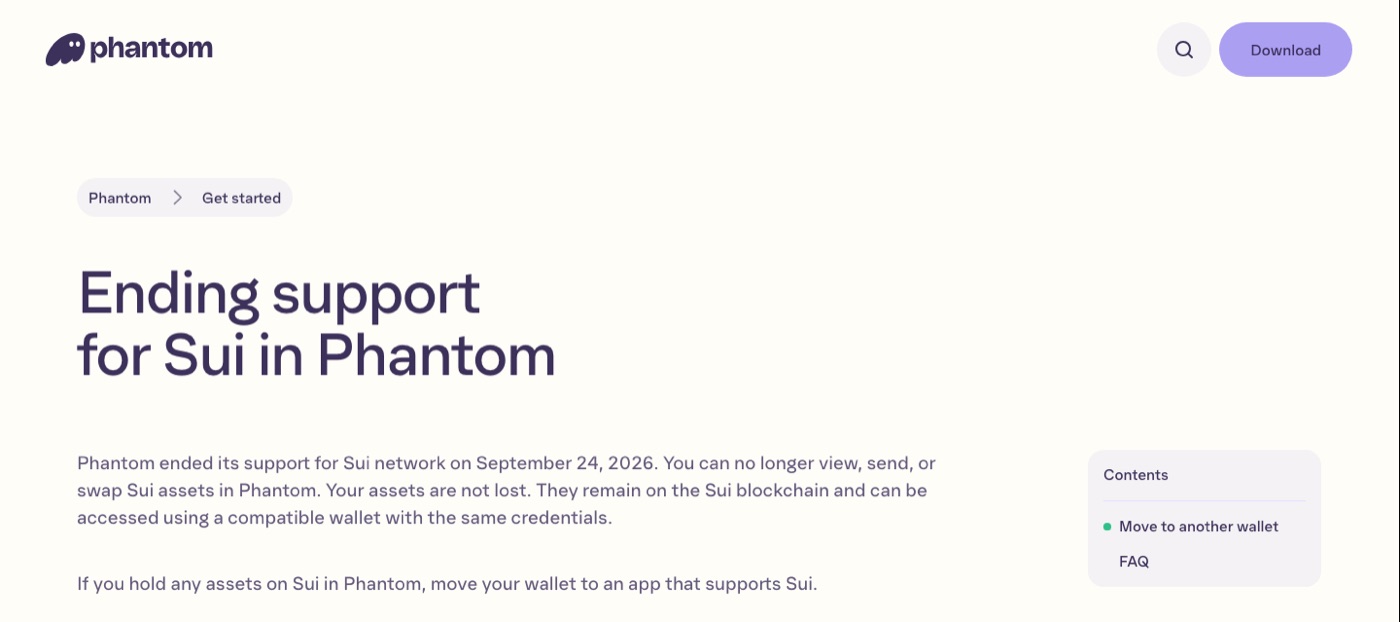
Sui has halted twice: about 2.5 hours in November 2024 and about six hours in January 2026. In May 2025, the Cetus exchange on Sui was exploited for about $223 million. That was an app bug, not a chain hack. But validators then blocked transactions involving about $162 million of the stolen funds and later voted on recovery. Good for victims, but it shows validators can act on specific transactions. Phantom also ended Sui support on 24 September 2026, so older wallet guides are wrong.
Five more networks worth knowing
- Stellar
- Payments and cash access. Native USDC, MoneyGram cash-in and cash-out through partner apps, and fees of 0.00001 XLM per operation. If you care more about remittances than DeFi variety, it could replace Aptos in the top ten.
- TON
- Telegram’s distribution plus native USDT ($651 million in stablecoins). The native coin was renamed Gram (GRAM) in June 2026, though some exchanges still label it TON. It went down for hours in August 2024 under heavy load.
- Cardano
- A distinct design (eUTXO), staking that doesn’t lock your ADA, and onchain governance since the Plomin upgrade in January 2025. The network split for about 14 hours in November 2025 before converging. Its USDCx is backed by USDC but isn’t issued by Circle.
- Celestia
- A data-availability layer for rollups, not a chain you’d use to send dollars. The 1 billion TIA was the starting supply, not a cap: inflation is about 2.5% and falling toward 1.5%.
- Plasma
- A stablecoin-focused EVM chain that launched in September 2025, with $1.3 billion in stablecoins and sponsored USDT0 transfers. Validators were permissioned at launch, and with about 13 months of history, it’s one to watch.
How to choose by what you want to do
| If you want to | Look at | Watch out for |
|---|---|---|
| Hold crypto yourself long term | Bitcoin, Ethereum | Key management is on you |
| Hold dollars yourself | Ethereum, Solana, Avalanche C-Chain (native USDC and USDT) | Issuers can still freeze tokens |
| Send small payments often | Solana, Stellar, XRP Ledger | Account reserves and recipient setup |
| Move USDT between exchanges | TRON, Ethereum, Solana | Pick the exact same network on both ends |
| Use DeFi | Ethereum (breadth), Solana (trading), BNB Chain (retail) | App risk is separate from chain risk |
| Trade perpetuals onchain | Hyperliquid | Liquidations and API outages |
One tip that saves money: the network fee is rarely the biggest cost. Exchange withdrawal fees and minimums usually are. Always match the asset and the network on both sides; the same token symbol can live on a dozen chains.
Questions
What counts as a Layer 1 blockchain?
Any base chain with its own consensus and ledger. It doesn’t need smart contracts: Bitcoin and the XRP Ledger count.
What’s the difference between a Layer 1 and a Layer 2?
A Layer 2 processes transactions off the main chain and posts results back to it. You get lower fees, but you also take on the L2’s operators, bridge and withdrawal rules.
Is the fastest blockchain the best one?
No. Advertised transactions-per-second figures mix different units (transactions, votes, messages, orders) and lab conditions. What matters is whether the network has the assets, apps and exchange support you need, and how it behaves under stress.
Which Layer 1 is the most decentralized?
There’s no honest league table. Validator counts mislead: a thousand validators run by a few companies can be less independent than a smaller, more varied set.
Sources
Network data: DefiLlama chains and stablecoins by chain, retrieved 22 October 2026. Stablecoin support: Circle’s USDC addresses and Tether’s supported protocols. Network details come from each project’s documentation and incident reports: Solana Alpenglow, BNB Chain Fermi, Sui January 2026 postmortem, XRPL reserves, Aptos supply, Celestia supply. Screenshots taken on 22 October 2026.